Every mover answers "yes" to the question "are my belongings insured?"; the right question is "on what basis, and for how much?". International removals insurance involves two separate mechanisms that are frequently confused. The first is CMR insurance: it covers the road carrier's legal liability under the CMR Convention and limits compensation not by the value of the goods but by their gross weight in kilograms. The second is all-risk cargo insurance: your goods are insured for the value you declare, with no need to prove fault on the carrier's part.
The difference shows up the moment something is damaged: when a fifteen-kilogram television is broken, the CMR limit is calculated on weight and covers only a small fraction of its value; if the same television is written into an all-risk policy at its declared value, the real value is paid. In this guide we explain the logic of the two systems, the SDR limit, exclusions, declaring values, damage-notification deadlines, the effect of packing and the questions you should ask when you receive a quote.
What Is the CMR Convention, and Why Is the Carrier Liable?
CMR is the 1956 convention governing the carrier's liability in international road transport, to which Turkey is also a party. Every truck travelling from Turkey to the UK or Germany moves under a CMR contract of carriage; the document describing the load is the CMR consignment note. The carrier is liable as a rule for loss, damage and delay occurring between the moment the goods are taken over and the moment they are delivered; the burden of proving it was not at fault lies with the carrier.
That liability is limited, however: Article 23 of the CMR caps compensation at 8.33 SDR per kilogram of gross weight. The SDR (Special Drawing Right) is a unit of account based on the IMF's currency basket and is converted into national currency at the daily rate. The formula: gross weight of the damaged item × 8.33 SDR = maximum compensation. If the real value is below this, the real value is paid; if above, only the limit. CMR insurance is the policy the carrier takes out in its own name to cover this liability; the insured party is the mover, not you.
CMR vs All-Risk Compared
| Criterion | CMR carrier liability | All-risk cargo insurance |
|---|---|---|
| Insured party | The carrier (mover) | The owner of the goods (you) |
| Basis of compensation | Gross kg × 8.33 SDR ceiling | Declared value |
| Fault requirement | The carrier's liability must be established; there are exemptions | No fault required; every risk not excluded is covered |
| Scope | Loss, damage and delay during carriage | Loading, carriage, transhipment, storage (if written into the policy), unloading |
| Light, high-value items | Inadequate (electronics, cameras, jewellery, artwork) | Protected at real value |
| Heavy, low-value items | Usually sufficient (books, boxes of clothing) | On declared value |
| Premium | Included in the freight charge | A percentage of declared value; separate line item |
| Deductible (excess) | Usually none | Fixed amount or percentage, depending on the policy |
In short: CMR exists on every shipment and protects the mover; all-risk is optional and protects you. The two are not alternatives; all-risk fills the gap CMR leaves behind.
How to Declare Values
The foundation of an all-risk policy is the inventory list. A second-hand market value is written for every box and piece of furniture; the total becomes the sum insured. Two principles:
- The under-insurance rule: if the declared total is below the real value of the goods, the insurer pays out on any damage in the same proportion. Declare half the value of your belongings and you will receive half the damage.
- Item-level declaration: high-value pieces such as electronics, musical instruments, artwork, antiques, bicycles and designer furniture go on separate lines with make, model and serial number. A lump-sum "household goods" declaration raises the question "was that item really in that box?" when a claim is made.
The declared value must also be consistent with the customs declaration. Invoices, bank statements, screenshots of second-hand listings or valuation reports are accepted as proof of value; for older items a photo and a reasonable market value are sufficient.
Exclusions in an All-Risk Policy
"All risks" is not absolute; in standard policies the following items are excluded or limited.
- Internal damage to boxes you packed yourself (PBO - packed by owner): if the box is intact on the outside but a plate inside is broken, the insurer treats it as a packing fault and does not pay. Where there is external damage (crushing, tearing, wetness), cover continues.
- Electrical and mechanical breakdown: a "won't switch on" complaint with no sign of external damage is excluded; physical damage (cracked screen, dented casing) is covered. A short video showing the item working before departure helps.
- Single pieces of a set: if one of six chairs is damaged, only that chair is paid for, not the whole set; for a dinner service, payment is made per broken plate.
- Pre-existing damage, damp and mould: scratches recorded on the collection report are excluded; damp in storage is not paid unless storage is written into the policy.
- Money, jewellery, documents: excluded under most policies; these do not travel in the truck anyway.
- Prohibited or undeclared goods: an item not on the list is not insured; goods seized by customs are not an insurable event.
- Deductible (excess): the fixed amount or percentage that remains with the insured on every claim. Small claims may fall below this threshold; ask about it explicitly when you get your quote.
How Professional Packing Changes Your Insurance Cover
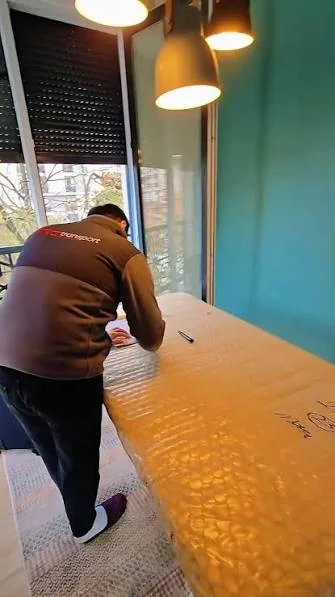
Who did the packing is one of the most critical lines in the policy. When our crew packs, the list records "packed by: mover" and internal damage to fragile items is covered as well; when you pack, only externally visible damage is paid. Leaving the packing of fragile items such as porcelain, glass, electronics, paintings and mirrors to us is not buying labour, it is buying cover. Packing your own boxes of clothes, books and toys causes no problem. The second effect is the quality of the record: our crew writes up the contents as each box is sealed and photographs existing scratches; the argument over "was that there before?" ends with that record.
Notifying Damage: Deadlines and Method
Even with the right policy, damage that is not notified in time and in the proper form is not paid. Article 30 of the CMR Convention sets out two distinct situations:
Visible damage: on the delivery report at the time of delivery
If a box is crushed, furniture is scratched or packaging is torn, the damage is written on the CMR consignment note or the delivery report at the moment of delivery and signed. A report with no damage note creates a presumption that the goods were delivered in sound condition; a note is made against every suspect box.
Hidden damage: in writing within 7 days
Damage not apparent from the outside (a vase found broken when unpacked, a cracked screen) is notified in writing within 7 days of delivery (Sundays and public holidays excluded); email is sufficient, with photos, box number and the relevant list line attached. Once the deadline has passed, the burden of proving the damage occurred in transit shifts to you.
What should a damage file contain?
- Signed delivery report and a copy of the CMR consignment note (with the damage note)
- The relevant line of the inventory list and its declared value
- Photos of the damage and the packaging; the packaging is not thrown away but kept until the inspection is complete
- Proof of value (invoice, listing, valuation)
- Repair estimate or a beyond-repair report
Checklist for Reading a Policy and a Quote
Unpack the phrase "insurance included" with these ten questions; the answers should be in writing.
- Is the insurance included CMR carrier liability or all-risk cargo insurance?
- For all-risk, what document is the sum insured based on: the inventory-list total or a lump sum?
- What is the premium rate, and is it shown as a separate line item in the quote?
- Is there a deductible (excess); is it per item or per claim?
- Is internal damage to boxes I pack myself covered or not?
- For electronics, is only physical damage covered, or breakdown as well?
- Is there a "pair and set" clause for sets?
- Is the storage period covered; for how many days?
- Who do I notify of damage, through which channel, and what is the hidden-damage deadline?
- Which insurance company issues the policy; can I see a specimen policy or the certificate?
The tenth question is the most important: an "insurance included" claim with no specimen policy to show for it usually describes CMR alone.
What determines the premium
- Total declared value; the premium is a percentage of this amount
- Breadth of cover: carriage only, or storage and transhipment as well
- Level of deductible; a higher deductible lowers the premium but leaves small claims uncovered
- Who packs, and the nature of the goods (artwork, antiques and musical instruments are assessed separately)
- Route and mode of transport: dedicated vehicle, groupage, transhipment or ferry crossing
Common Mistakes
- Accepting the word "insured" without asking about the CMR versus all-risk distinction.
- Undervaluing to save on premium; proportionally reduced payment when damage occurs.
- Packing fragile items yourself and assuming internal damage is covered.
- Not recording serial numbers and working condition for electronics.
- Signing the delivery report without reading it; the right to claim visible damage is lost at that moment.
- Unpacking late and reporting hidden damage after 7 days.
- Throwing away damaged packaging; no inspection can be carried out.
- Declaring one value to customs and another to the insurer.
Case Study: A Broken Television and a Cracked Vase on a Move to London
A family moving from Istanbul to London prepares their inventory list box by box with values; two televisions, a laptop and an antique vase are on separate lines with serial numbers and photos. The packing of fragile items is left to our crew; the family packs the boxes of books and clothes themselves. The list total is entered on the all-risk policy as the sum insured; premium, deductible and exclusions appear as separate lines in the quote. In London, 65 boxes are counted; one box has a crushed corner and the report is annotated "box 14 externally damaged, contents to be checked". The box is opened the same day and the television's screen is found cracked; notification is made with photos and the serial number. Four days later another box is opened and the vase is cracked; written hidden-damage notification is sent within the 7 days and the packaging is kept. Because both items were packed by the mover, the internal-damage exclusion does not apply; the insurer pays on the declared values, less the deductible. Had the television been left to CMR alone, compensation would have been capped at 8.33 SDR × gross weight. Items left uncovered: zero.
Why REG Transport?
- CMR insurance included on every shipment; for customers who want it, optional all-risk cover on declared value is written into the quote as a separate line.
- Premium, deductible and exclusions explained in writing at the quotation stage; the phrase "insurance included" is never left hollow.
- Professional packing crew; the internal-damage exclusion falls away for fragile items, and every box is entered on the list.
- Transfer-free transport with our own fleet and controlled holding at our Istanbul, Gaziantep, London and Frankfurt warehouses.
- Signed, photographed reports at loading and delivery; your coordinator prepares the damage file together with you.
- A single point of contact; written, itemised quote the same day.
Frequently Asked Questions
Isn't CMR insurance enough? Why should I take out all-risk as well?
CMR limits compensation by weight and protects the mover; it is adequate for books and clothing, inadequate for electronics and furniture. All-risk protects you on declared value.
How should I set the declared value?
At what the same item would fetch second-hand today. Undervaluing leads to proportionally reduced compensation, overvaluing to questions at customs; list valuable items separately with their serial numbers.
Are the boxes I pack myself insured?
External damage (crushing, tearing, wetness) is covered; breakage inside a box that is intact on the outside is treated as a packing fault and is not paid. Leave the packing of fragile items to us.
When must I report damage?
Have visible damage written on the report at the time of delivery. Report hidden damage in writing within 7 days of delivery (CMR Art. 30). Keep the packaging until the inspection is complete.
Are my belongings insured while in storage?
A standard transit policy covers the carriage; storage is covered only if written into the policy. If you will be using storage, say so in the quote and the storage period is added to the policy.
Let's Insure Your Belongings at Their True Value
Fill in the quote form and we will set out the CMR cover, the all-risk option, premium and deductible terms in writing, item by item, the same day. Related guides: how to prepare an inventory list, complete guide to moving household goods abroad, shipping new furniture from Turkey to the UK; services: international household removals, commercial freight and vehicle transport.